Cameroon’s Approach to Maintaining Stable Banking Operations in Cameroon Through Proactive Measures 2024
Cameroon’s Innovative Approach to Safeguarding Bank Liquidity
In the dynamic landscape of financial security, Cameroon has taken a proactive step with the establishment of the Fund for Deposits and Consignments (FDC). This strategic move is designed to bolster the liquidity of banks and secure idle funds, which are crucial for the stability and growth of the national economy.
The FDC, a brainchild of the Cameroonian government, operates under a clear mandate: to collect, secure, and optimize the returns on untapped financial resources. These resources, often lying dormant in various sectors, can now be directed towards supporting public policies and national development initiatives.
A pivotal decree signed by Prime Minister Joseph Dion Ngute on December 1, 2023, marked the beginning of a new era for the FDC. The decree outlines the modalities for the transfer of funds and securities to the FDC, ensuring a structured and transparent process. Financial institutions, along with public and private enterprises, are given a six-month window to comply with the transfer requirements, setting a deadline of May 31, 2024.

The decree empowers the FDC to conduct external audits and on-site missions to verify the sincerity of the deposits post-deadline. This measure is intended to maintain the integrity of the funds and prevent any discrepancies. Furthermore, the FDC is not merely a repository for these funds; it actively creates accounts with the concerned institutions, allowing for seamless debiting and crediting without carting resources away.
One of the key objectives of this initiative is to prevent excessive liquidity outflow, which could potentially trigger inflationary pressures in the economy. Cameroon is setting up a double guarantee system by debiting and creating special FDC accounts within financial institutions. This system not only secures the funds but also ensures they are readily available for mobilization when needed.
The operationalization of the FDC has been a significant milestone, with Richard Evina Obam appointed as the Director General. His leadership is expected to drive the FDC’s mission forward, leveraging his experience as the former Director General of the Autonomous Amortization Fund (CAA).
Cameroon’s approach serves as a model for other nations, showcasing how deposit and consignment funds can be powerful instruments for development. The FDC’s role in managing idle funds is not just about securing assets; it’s about creating opportunities for growth and development, reflecting a commitment to financial prudence and strategic foresight.
As the deadline approaches, the anticipation grows for the positive impact the FDC will have on Cameroon’s financial landscape. With careful management and strategic deployment of funds, the FDC is poised to become a cornerstone of Cameroon’s economic stability and growth.
The Fund for Deposits and Consignments (FDC) in Cameroon serves as a pivotal financial mechanism with a multitude of benefits aimed at enhancing the country’s economic stability and development. Here are some of the key advantages:

1. **Resource Optimization**: The FDC centralizes and manages untapped resources, which include regulated savings, deposits from notaries or legal professions, administrative deposits and guarantees, funds from national savings banks, social security funds, pension funds, and insurance and guarantee funds. This consolidation allows for the secure and efficient utilization of funds that would otherwise remain idle.
2. **Supporting Public Policies**: By collecting and securing these resources, the FDC plays a significant role in directing them towards supporting public policies. This strategic allocation of funds aids in the implementation of government initiatives and development projects, thereby fostering national growth.
3. **Long-term Returns**: The FDC is not just a repository for funds; it actively seeks to make long-term returns on these resources. This approach ensures that the funds contribute to the economy’s growth, providing a sustainable financial model for development projects.
4. **Development Financing**: In other countries, similar funds have been instrumental in financing social housing, universities, business development, and energy transition projects. Cameroon’s FDC is expected to follow suit, becoming a key tool for financing such vital development operations within the country.
5. **Crisis Management**: The resources collected by the FDC can also be utilized by the government to ensure and guarantee financing for various operations that serve the interest of the population. This includes real estate projects, supporting the economy, and more effectively addressing crises, such as natural disasters.
6. **Economic Stability**: By preventing excessive liquidity outflow, the FDC helps to maintain economic stability. The special accounts created within financial institutions provide a double guarantee system, securing the funds and ensuring they are available for mobilization when needed.
7. **Transparency and Control**: The FDC’s operational framework includes provisions for external audits and on-site missions to verify the sincerity of the deposits. This transparency and control mechanism instils confidence in the system and prevents financial discrepancies.
The establishment of the FDC in Cameroon represents a forward-thinking approach to financial management, with the potential to positively impact the country’s economic landscape. As the FDC continues to evolve, it will likely become an integral part of Cameroon’s sustainable development and financial security strategy.
The general management of the Caisse des Dépôts et Consignations du Cameroun (CDEC) initiated, on May 13, technical exchanges with the Professional Association of Credit Establishments of Cameroon (Apeccam). The objective of this high-level meeting is to complete the reflection on the safeguards to be put in place to prevent the process of transferring funds and assets escheated from banks to the new state structure, from being done without disruption to the national banking sector. “Imagine such important resources to be mobilized through institutions whose vocation is to collect resources from savers and different economic actors. There is an important issue which requires that the reform be carried out in the most secure possible details because, you see, the banking profession lives more from risk management than anything else. So, it is a question of ensuring that these resources which belong to various actors are well supervised and that the reform is successful,” underlines the vice-president of Apeccam, Jean-Paul Missi, also general director of Crédit Land of Cameroon (CFC).
Created in 2008, the CDEC, which had to wait 15 years before entering into activity, has the mission of collecting, securing and making profitable in the long term generally “idle” resources to direct them towards supporting public policies. Said resources have been on deposit or consignment, for several decades for some, with the legal professions, credit establishments, insurance companies, public administrations, public and private establishments and companies and even natural and legal persons. These entities have until May 31 to transfer these funds to the CDEC, by the Prime Minister’s decree of December 1, 2023, setting the terms of transfer of funds and values assigned to this structure. Banks, in particular, have expressed fears about a possible boomerang effect, given the amount of cash that the expected transfers could cause them to lose. For more than a year, they have been slowing down to delay this deadline as long as possible.
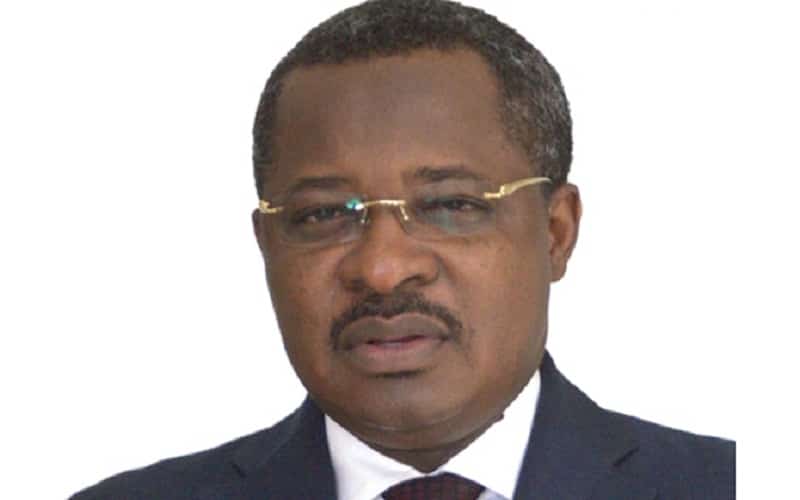 Richard Evina Obam, CEO of the Caisse de dépôt du Cameroun
Exposure level
The public authorities are delaying by taking precautions taken upstream to avoid any risk to the banking system, particularly in the management of liquidity risk. They also ensure that they have taken into account the specificities of each actor. “Among the problems raised by the bankers, there are some that have already been resolved. The biggest is the impact that transfers could have on their balance sheet and prudential situations. We reiterated to them that the Prime Minister’s decree already largely solves this problem because we will open accounts within the banks themselves. There will be no movement of funds. Therefore, there will be no impact on their balance sheet and prudential situations,” guarantees the director general of the CDEC, Richard Evina Obam. Other specific measures have been planned, from which credit institutions could benefit at their request and depending on their level of exposure in terms of financial commitment.
Moratorium
The top management of the Caisse des Dépôts et Consignations is in any case putting its cards on the table and swearing that there will be no new moratorium after the May 31 deadline. “It would be one moratorium too many. The public authorities waited 15 years! The CCDEC was created in 2008 and the public authorities, based on the banks’ concerns, waited until January 2023 to appoint social directors and put this institution into service. Likewise, the Prime Minister’s decree did not take into account the requirements of higher texts which provided for transfers 6 months after the appointment of social leaders. But, the Prime Minister decided that it would be 6 months from the signing of his decree. Which means that there was another de facto moratorium. Another moratorium would be too much. We are based on a reform; there is a schedule and a business plan that must be able to be executed. And I think that today’s meeting allowed us to resolve our differences of opinion on the issue and that we now have a common understanding of the provisions of the Prime Minister’s decree. The interviews and meetings we had with banking professionals enabled us to move forward in resolving practical problems. So, there is only one thing left: transfer the funds allocated to the CDEC,” says Richard Evina Obam.
For the record, since the start of the operationalization of the Caisse des Dépôts et Consignations, some banks and players in the non-banking sectors have spontaneously made declarations and transfers. Thus, for example, Banque Atlantique Cameroun (BAC), signed on November 2, 2023, a pilot partnership with this institution aimed at supervising the transfer and management of funds and values devolved to it. An agreement of the same nature was initiated on October 31, 2023, with the insurance company Allianz Cameroun, which enabled the effective transfer of 1.5 billion CFA francs to the CDEC, which aims to play a leading role in financing the economy. On December 15, 2023, the CEO of this fund and the Minister of Finance signed another agreement which provides that public accountants, in particular general paying treasurers, will serve as relays at the national level for deposit, withdrawal, deposit and designation operations.